Featured Pathways

More pathways

Banking Essentials - Part I

This pathway will walk us through the basics of banks, starting with some of the different types and their main functions, then starting to look at the regulation faced by the banks, both before and after the Global Financial Crisis.

Greenwashing

Greenwashing is the act of distributing false information about something being more environmentally friendly than it actually is.

More pathways

Book a demo

Ready to get started?

Plans & Membership

Our Platform

Expert led content

+1,000 expert presented, on-demand video modules

Learning analytics

Keep track of learning progress with our comprehensive data

Interactive learning

Engage with our video hotspots and knowledge check-ins

Testing & certification

Gain CPD / CPE credits and professional certification

Managed learning

Build, scale and manage your organisation’s learning

Integrations

Connect Finance Unlocked to your current platform

Featured Content

More featured content

Tackling the Cost of Living Crisis

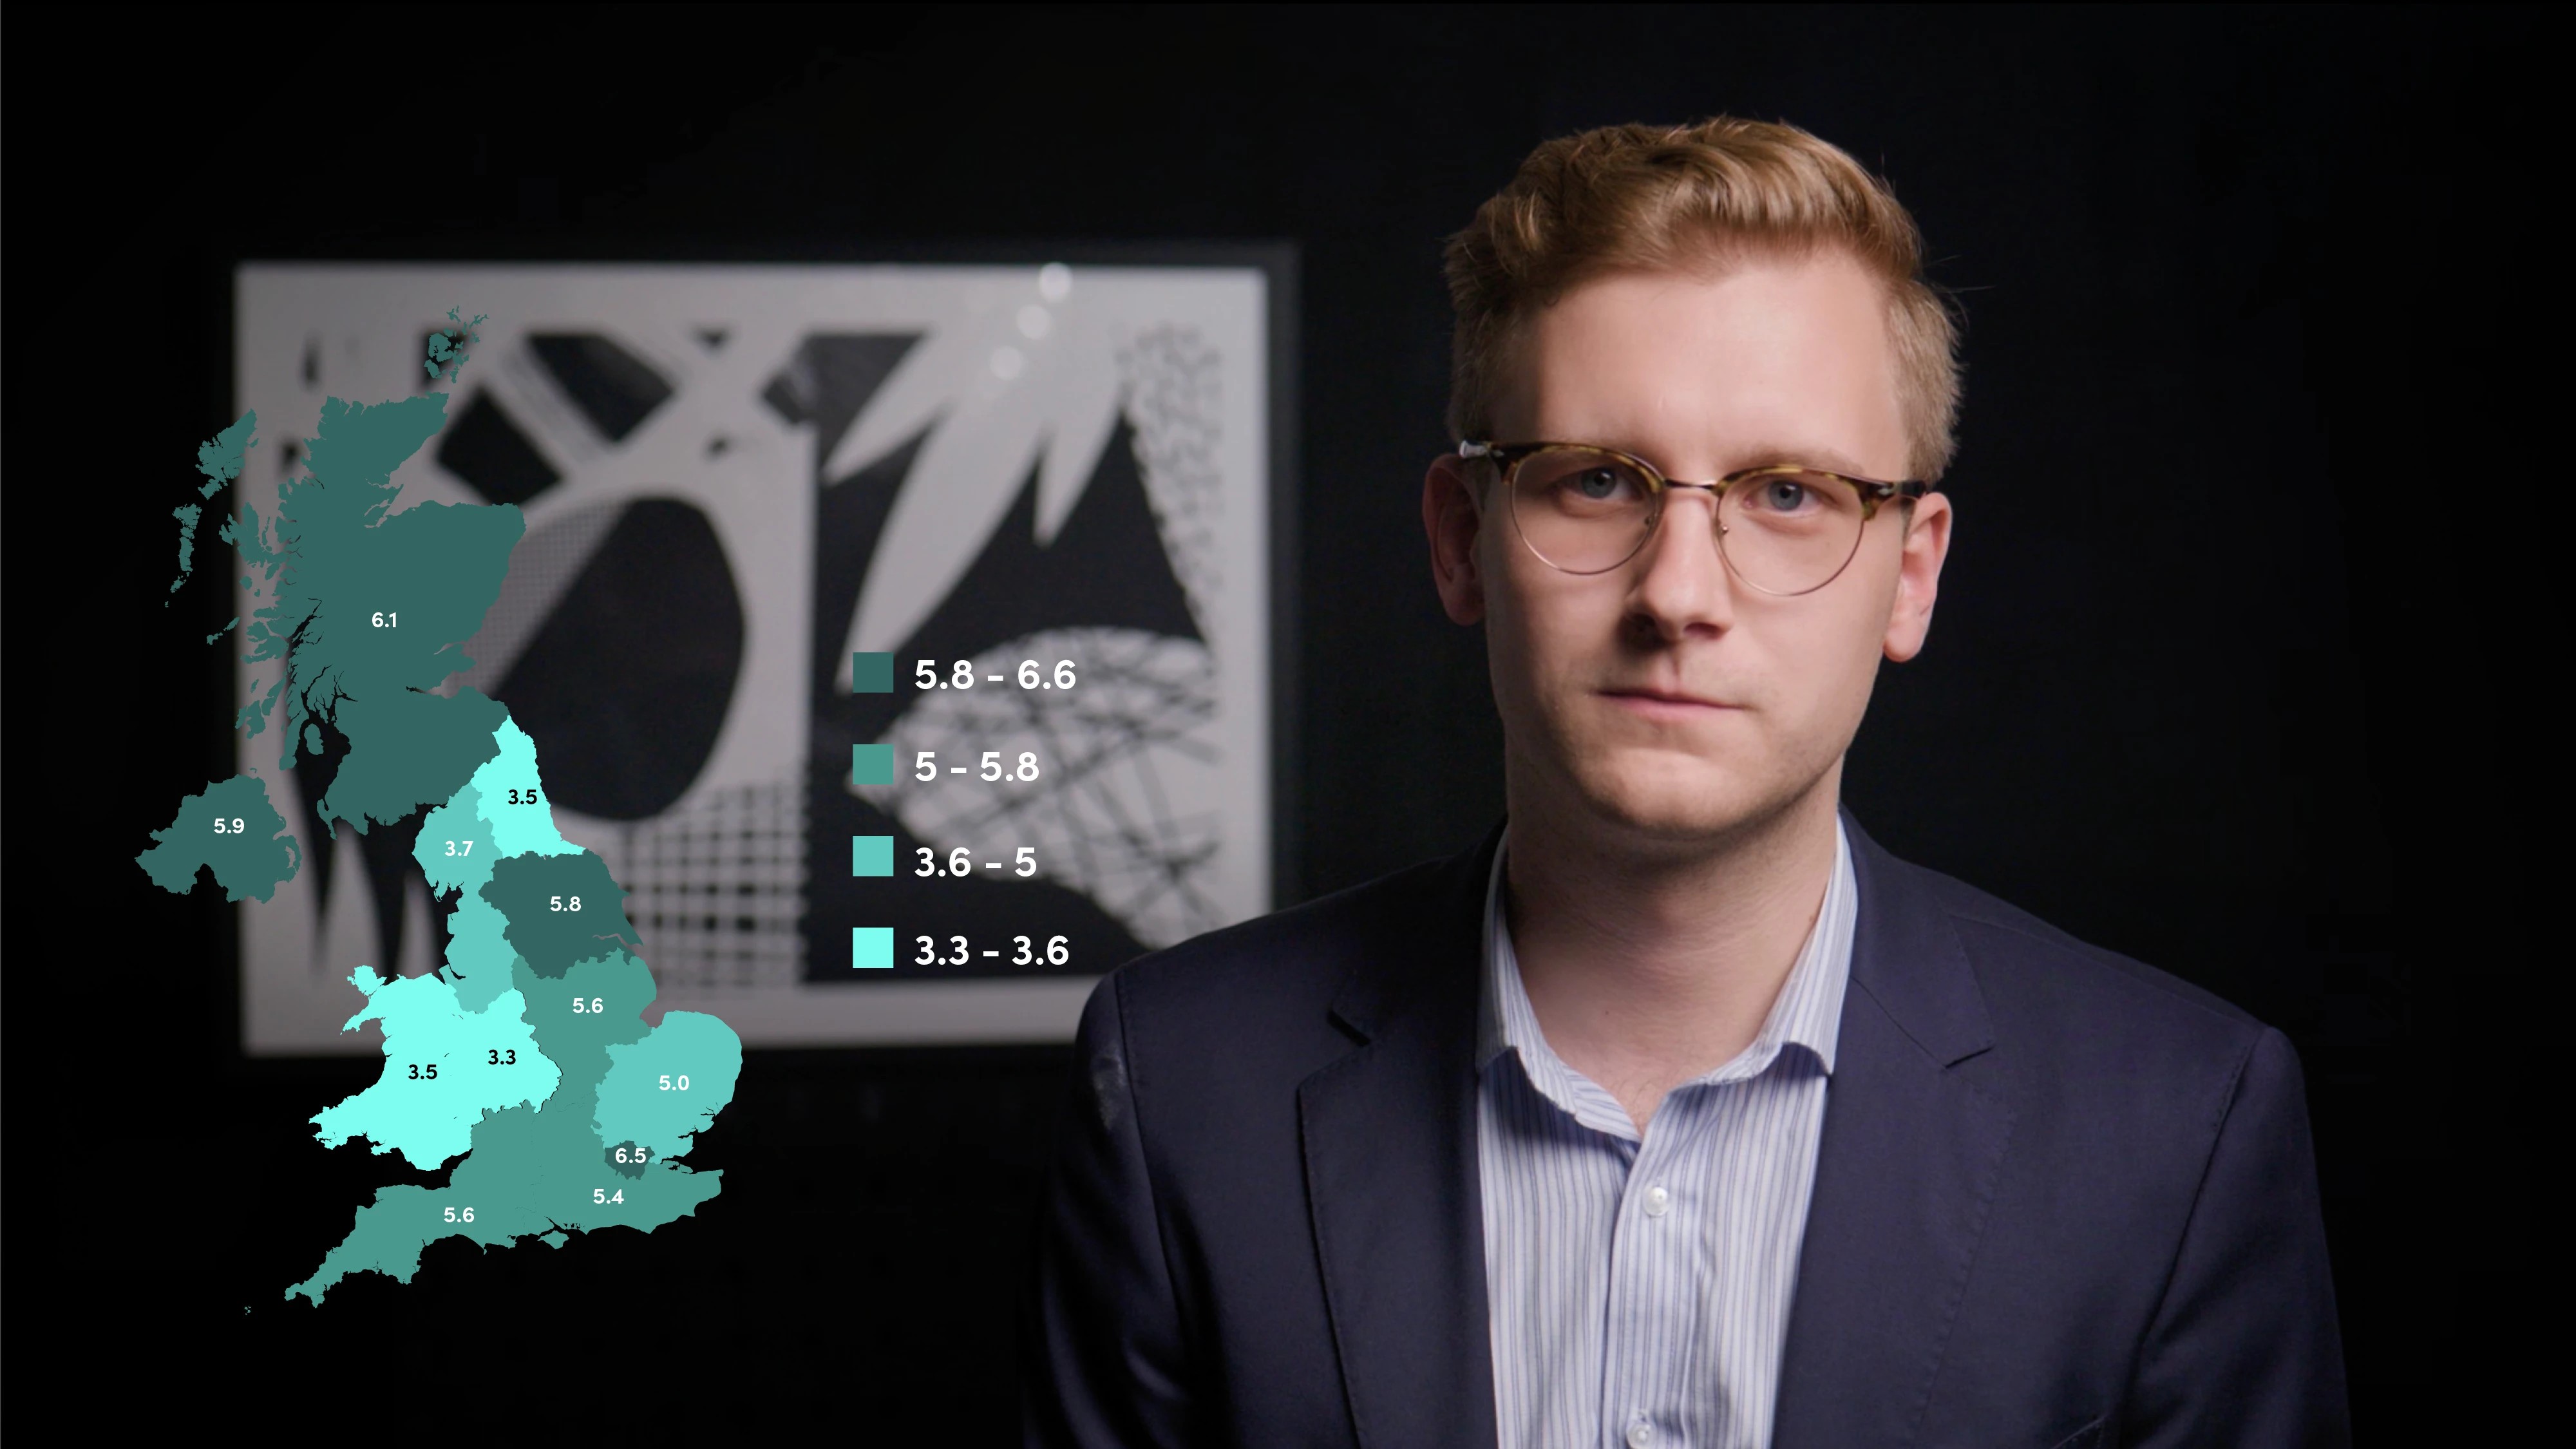
In this video, Max discusses the cost-of-living crisis currently enveloping the UK. He examines its impact on households as well as the overall economy.

Introduction to Corporate Valuation

In this video on Corporate Valuation, Sarah Martin covers the basic background to corporate valuations, who uses them, why they are needed and also outlines the factors that impact valuation.

More featured content

Book a demo

Ready to get started?

Featured Pathways

More pathways

Banking Essentials - Part I

This pathway will walk us through the basics of banks, starting with some of the different types and their main functions, then starting to look at the regulation faced by the banks, both before and after the Global Financial Crisis.

Greenwashing

Greenwashing is the act of distributing false information about something being more environmentally friendly than it actually is.

More pathways

Book a demo

Ready to get started?

Plans & Membership

Our Platform

Expert led content

+1,000 expert presented, on-demand video modules

Learning analytics

Keep track of learning progress with our comprehensive data

Interactive learning

Engage with our video hotspots and knowledge check-ins

Testing & certification

Gain CPD / CPE credits and professional certification

Managed learning

Build, scale and manage your organisation’s learning

Integrations

Connect Finance Unlocked to your current platform

Featured Content

More featured content

Tackling the Cost of Living Crisis

In this video, Max discusses the cost-of-living crisis currently enveloping the UK. He examines its impact on households as well as the overall economy.

Introduction to Corporate Valuation

In this video on Corporate Valuation, Sarah Martin covers the basic background to corporate valuations, who uses them, why they are needed and also outlines the factors that impact valuation.

More featured content

Book a demo

Ready to get started?

Book a demo

Ready to get started?

Private credit

Private credit

Glossary

Private credit

Reviewed by Jack Shrimpton, Senior Finance Content and Production Manager at xUnlocked · Last updated August 2026 Private credit is debt financing provided mainly by non-bank lenders through privately negotiated instruments that are not publicly traded. It most commonly refers to direct loans made to companies by private credit funds, asset managers and institutional investors, rather than debt issued through public bond markets or distributed widely through syndicated loans. There is no universally accepted definition. Some sources use private credit narrowly to mean direct corporate lending, while others include asset-based finance, fund finance, distressed credit and other private debt strategies. Estimates therefore vary, but the broader global private debt market had grown to more than $2.5 trillion in assets under management by 2025. Using a narrower definition focused mainly on non-bank direct lending, the Financial Stability Board estimated the market at between $1.5 trillion and $2 trillion at the end of 2024. Historically funded mainly by institutional investors such as pension funds and insurers, private credit has primarily served mid-sized businesses but increasingly finances larger companies. It is also becoming more accessible to individual investors through evergreen and semi-liquid fund structures.

What are the main types of private credit?

  • Direct lending. Privately negotiated loans made directly to companies by one lender or a small group. They are often senior secured and may fund expansion, refinancing or private-equity-backed acquisitions.
  • Asset-based and specialty finance. Lending secured against assets or cash flows, such as equipment, property, receivables, consumer loans or royalties.
  • Mezzanine and subordinated debt. Debt that ranks below senior borrowing but ahead of equity. It carries greater risk and may include warrants or other forms of equity participation.
  • Distressed and special-situations credit. Financing for companies in financial difficulty, or the purchase of their existing debt at a discount. Returns depend heavily on restructuring outcomes and recovery values.
  • Fund finance. Lending to investment funds, secured against investor commitments, portfolio assets or expected cash flows. This includes subscription facilities and financing based on a fund’s net asset value.

Why has private credit grown so quickly?

Much of the growth traces back to banks pulling back from certain types of corporate lending after the 2008 financial crisis, as tighter capital and regulatory requirements made it less attractive for them to hold higher-risk loans on their balance sheets. Non-bank lenders filled that gap, particularly for mid-sized companies that were too small for the public bond markets but wanted more tailored terms than a standard bank loan could offer. That dynamic has continued: ongoing bank capital reforms keep pushing certain lending exposures toward non-bank channels, while borrowers increasingly value the speed, certainty and flexibility that a privately negotiated deal with a single lender (or small club of lenders) can offer compared with a broadly syndicated loan.

What are the main challenges and risks in private credit?

  • Borrower credit and leverage risk. Private credit borrowers are often smaller, more highly leveraged or less able to access conventional markets. Floating-rate loans can also become harder to service when interest rates rise.
  • Untested at its current scale. The market showed some resilience during the COVID-19 pandemic but has not experienced a prolonged downturn at its current size and level of interconnectedness.
  • Valuation and liquidity. Private loans trade infrequently, so valuations rely more heavily on models and periodic assessments than observable market prices. Semi-liquid funds may also offer investors more frequent redemptions than the underlying loans can easily support.
  • Interconnectedness. Private credit funds are linked to banks, insurers and private equity firms through financing arrangements, investments and shared borrowers. Stress in one part of the system could therefore affect others.
  • Data and monitoring gaps. Reporting is less harmonised and comprehensive than in banking and public markets, making it harder to assess leverage, concentrations and risks across the sector.
For background on the public debt markets that private credit sits alongside, and increasingly competes with, as a source of corporate finance, see The Role of Credit Markets, a video module presented by Lindsey Matthews, Banking and Risk Management Specialist. The video covers how companies and governments raise debt through the public bond markets, including the investment-grade versus sub-investment-grade distinction that also shapes how private credit deals get priced and structured.

Frequently asked questions

Is private credit the same as private equity?
No, though the two are closely linked. Private equity firms buy and manage companies using a mix of their own capital and borrowed money; private credit funds are often the ones providing that borrowed money, particularly for the debt financing behind private-equity-backed acquisitions. Private credit investors are lenders with a contractual claim to interest and principal, not owners with a stake in the company's upside.

How is private credit different from a broadly syndicated loan (BSL)?
A broadly syndicated loan is arranged by one or more banks and distributed to a relatively large group of investors. Its terms are generally more standardised, and it may trade in the secondary market.
A private credit loan is usually negotiated with one lender or a small group, offers more tailored terms and is traded less frequently. However, the boundary between the two markets is becoming less distinct.

Why are regulators paying closer attention to private credit now?
The market has expanded rapidly and its links with banks, insurers and private equity firms are deepening.
Private credit does not necessarily present a systemic risk by itself. However, borrower leverage, valuation uncertainty, limited transparency and growing interconnectedness could amplify stress during a severe downturn.

Related terms

Related Video Modules