





Risk-Weighted Assets
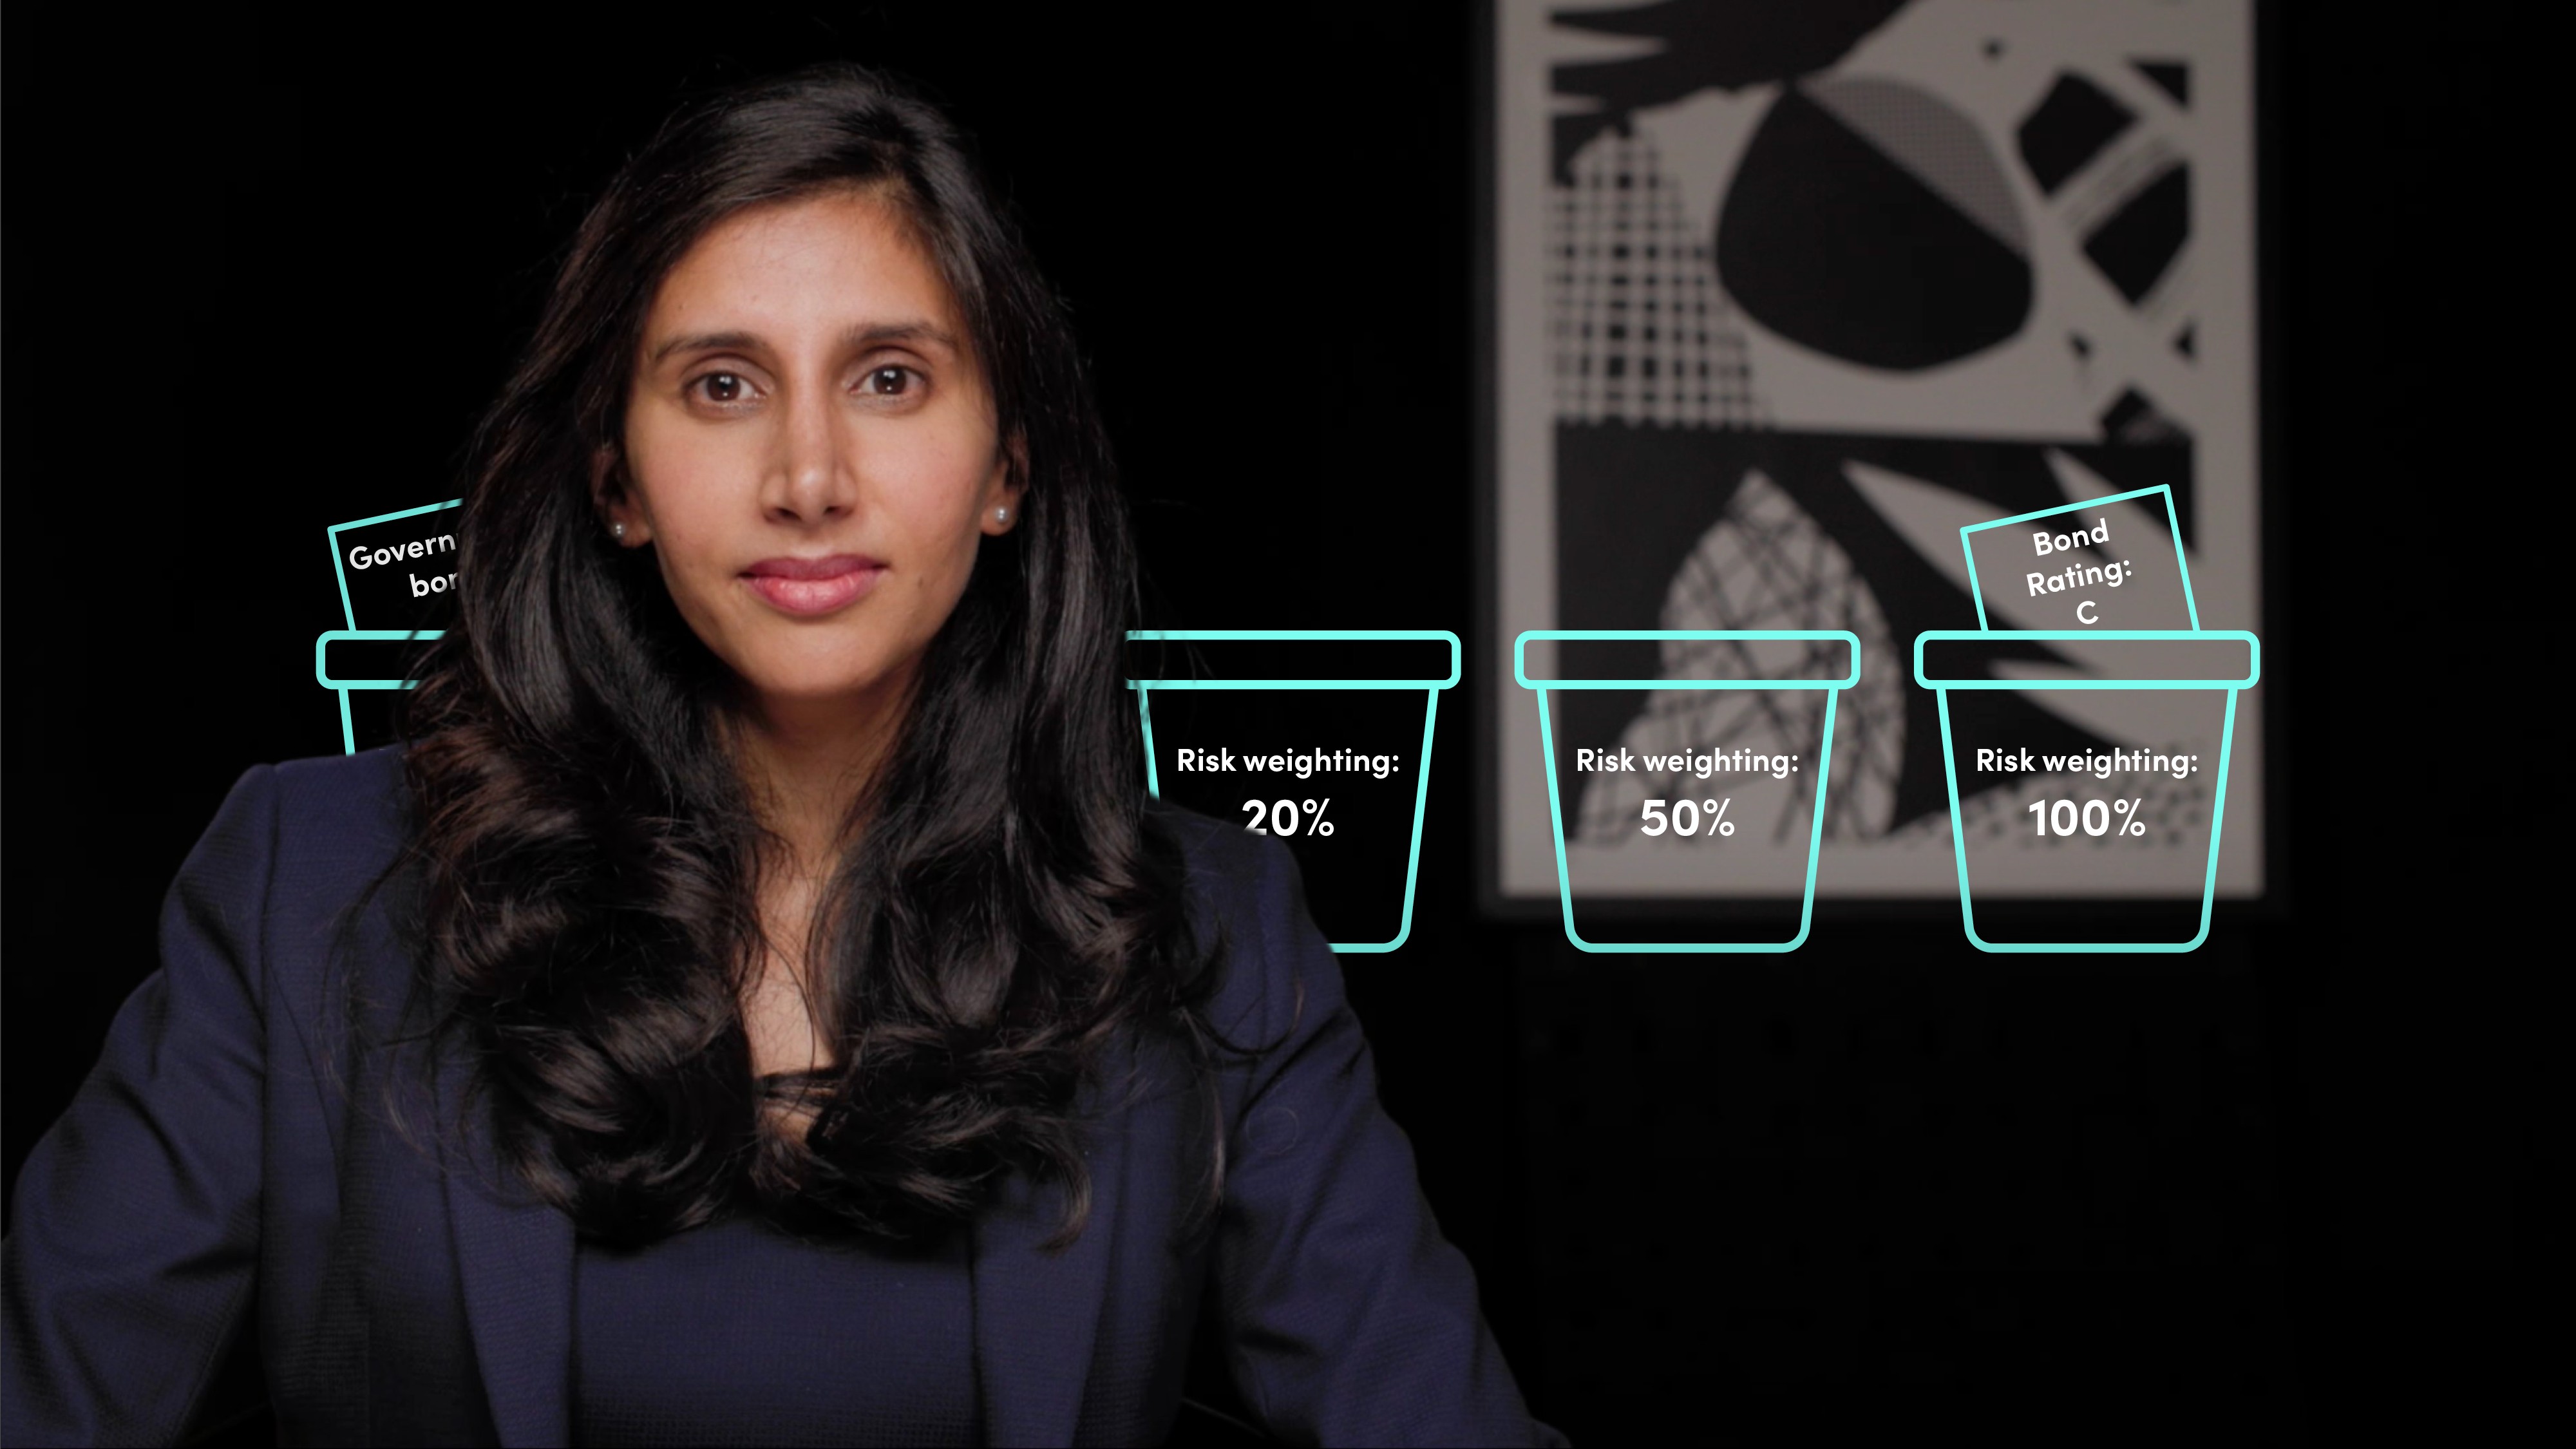
Reviewed by Jack Shrimpton Senior Finance Content and Production Manager at xUnlocked · Last updated July 2026 Risk-weighted assets, or RWA, are a measure of a bank’s assets and exposures adjusted for risk. They are used in banking regulation to determine how much capital a bank needs to hold. The basic idea is simple: not all assets carry the same level of risk. A government bond issued by a highly rated sovereign is usually treated as much lower risk than an unsecured corporate loan. A bank holding mainly low-risk assets will therefore usually have lower RWA than a bank with the same total assets but a riskier loan book. Under the standardised approach, banks apply regulatory risk weights to different types of exposure. For example, a low-risk sovereign exposure may receive a very low or zero risk weight, while an unsecured corporate loan may receive a much higher risk weight. The risk-weighted amount is calculated by multiplying the exposure amount by the relevant risk weight. RWA is most commonly associated with credit risk, but the overall RWA figure used in capital ratios can also include other risk types, such as market risk, operational risk and counterparty credit risk. It can also include off-balance sheet exposures, after applying the relevant conversion factors. Banks can calculate RWA using the standardised approach, where risk weights are set by regulation, or, for some larger and more complex banks, using internal ratings-based approaches approved by supervisors. Internal models can make capital requirements more risk-sensitive, but they can also produce lower RWA than standardised rules. For that reason, Basel 3.1 introduces an output floor, which limits how far internally modelled RWA can fall below the amount calculated using standardised approaches.
Worked example: calculating risk-weighted assets
Cash and eligible government bonds: £50m exposure × 0% risk weight = £0m RWA