Featured Pathways

More pathways

Banking Essentials - Part I

This pathway will walk us through the basics of banks, starting with some of the different types and their main functions, then starting to look at the regulation faced by the banks, both before and after the Global Financial Crisis.

Greenwashing

Greenwashing is the act of distributing false information about something being more environmentally friendly than it actually is.

More pathways

Book a demo

Ready to get started?

Plans & Membership

Our Platform

Expert led content

+1,000 expert presented, on-demand video modules

Learning analytics

Keep track of learning progress with our comprehensive data

Interactive learning

Engage with our video hotspots and knowledge check-ins

Testing & certification

Gain CPD / CPE credits and professional certification

Managed learning

Build, scale and manage your organisation’s learning

Integrations

Connect Finance Unlocked to your current platform

Featured Content

More featured content

Tackling the Cost of Living Crisis

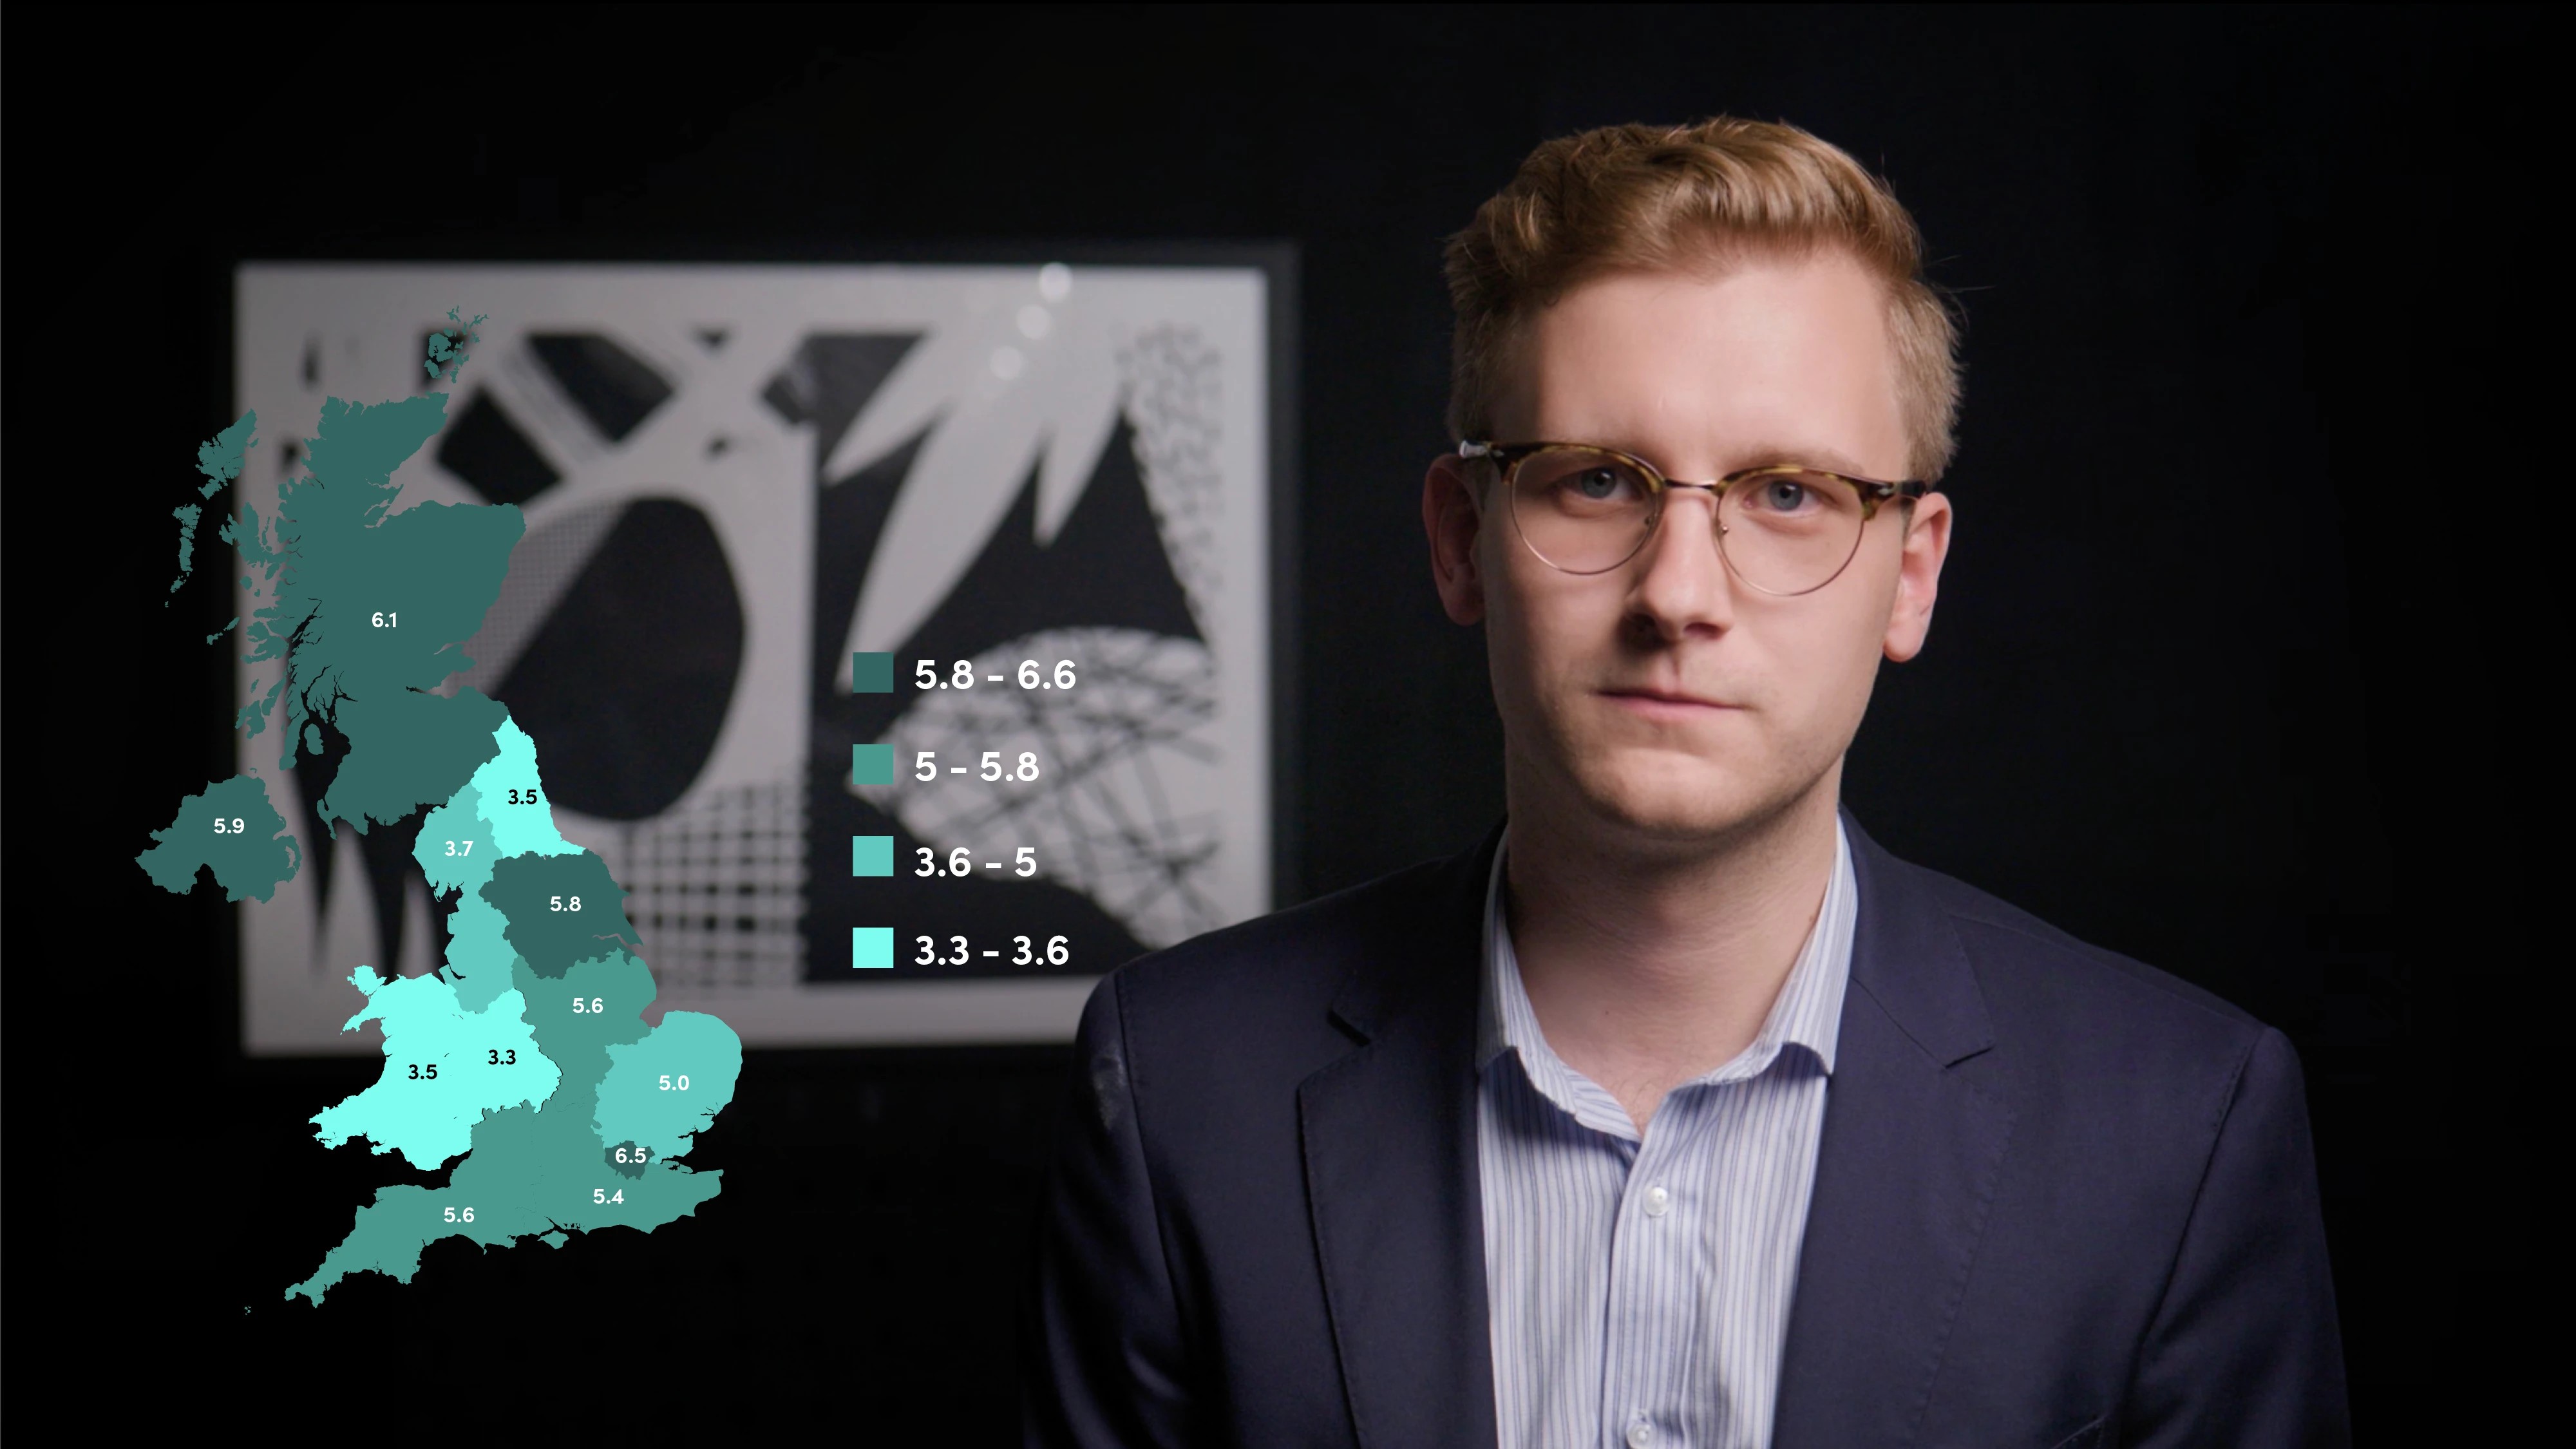
In this video, Max discusses the cost-of-living crisis currently enveloping the UK. He examines its impact on households as well as the overall economy.

Introduction to Corporate Valuation

In this video on Corporate Valuation, Sarah Martin covers the basic background to corporate valuations, who uses them, why they are needed and also outlines the factors that impact valuation.

More featured content

Book a demo

Ready to get started?

Featured Pathways

More pathways

Banking Essentials - Part I

This pathway will walk us through the basics of banks, starting with some of the different types and their main functions, then starting to look at the regulation faced by the banks, both before and after the Global Financial Crisis.

Greenwashing

Greenwashing is the act of distributing false information about something being more environmentally friendly than it actually is.

More pathways

Book a demo

Ready to get started?

Plans & Membership

Our Platform

Expert led content

+1,000 expert presented, on-demand video modules

Learning analytics

Keep track of learning progress with our comprehensive data

Interactive learning

Engage with our video hotspots and knowledge check-ins

Testing & certification

Gain CPD / CPE credits and professional certification

Managed learning

Build, scale and manage your organisation’s learning

Integrations

Connect Finance Unlocked to your current platform

Featured Content

More featured content

Tackling the Cost of Living Crisis

In this video, Max discusses the cost-of-living crisis currently enveloping the UK. He examines its impact on households as well as the overall economy.

Introduction to Corporate Valuation

In this video on Corporate Valuation, Sarah Martin covers the basic background to corporate valuations, who uses them, why they are needed and also outlines the factors that impact valuation.

More featured content

Book a demo

Ready to get started?

Book a demo

Ready to get started?

Accounts, Payments and Everyday Banking
Accounts, Payments and Everyday Banking

Simon Thompson

Sustainable Finance Expert

Explore the core products and services of retail banking, from current accounts and payments to cards, savings, digital tools and relationship banking.

Explore the core products and services of retail banking, from current accounts and payments to cards, savings, digital tools and relationship banking.

Subscribe to watch

Access this and all of the content on our platform by signing up for a 7-day free trial.
Accounts, Payments and Everyday Banking

7 mins 19 secs

Key learning objectives:

  • Describe the role of current accounts, payments and cards

  • Distinguish between common savings products and interest-rate structures

  • Explain how digital tools support everyday money management

  • Recognise why cash access and inclusion remain important

  • Explain the role of bundling and relationship banking

Overview:

Everyday retail banking is built around products that help customers receive, store, spend and save money. Current accounts often act as the centre of the customer relationship, while also providing banks with an important source of funding. Payments, cards and digital banking tools support daily financial activity, while savings products help customers build resilience and plan for future goals. Although digital services continue to expand, access to cash remains important for many customers. Banks increasingly combine products through relationship banking, creating opportunities for deeper customer relationships when products are relevant and responsibly offered.

Subscribe to watch

Access this and all of the content on our platform by signing up for a 7-day free trial.

Summary
Why are current accounts central to retail banking?

Current, checking or transaction accounts act as a financial hub for many customers. They are used to receive income, pay bills, transfer money, withdraw cash and manage everyday spending, and are usually linked to a debit card.

They are also strategically important to banks. Regular account activity creates frequent customer engagement and can support wider relationships across savings, lending and other products. Customer deposits are also an important source of funding for many retail banks, helping finance lending such as mortgages and personal loans.

How do payments, cards and digital services support everyday banking?

Payments allow customers to move money through cards, bank transfers, direct debits, standing orders, cash and mobile wallets. Although payment habits differ between markets, customers generally expect transactions to be fast, convenient and secure.

Debit cards use money already held in a customer’s account, while credit cards provide revolving borrowing up to an agreed limit. Digital banking has expanded these services further through tools such as card controls, alerts, budgeting features, spending insights and in-app support. Increasingly, customers judge providers not only on their financial products, but also on how easy and useful their digital services are.

How do savings products meet different customer needs?

Savings can help customers prepare for future purchases, manage unexpected costs, build emergency funds and plan for retirement.

Different products offer different trade-offs between access and return. Instant-access accounts allow customers to withdraw money quickly, while notice accounts require advance notice and may offer higher interest in return for reduced access. Fixed-term deposits lock money away for an agreed period, often at a fixed rate.

Savings rates can be fixed or variable, while some jurisdictions also provide tax-advantaged savings arrangements. Digital tools such as automated transfers, round-ups and savings goals can make regular saving easier.

Why do inclusion and relationship banking matter?

Despite the growth of digital payments, cash remains important for customers who use it for budgeting, emergency back-up or because digital services are difficult to access. Maintaining access to essential banking services therefore remains an important part of financial inclusion.

Banks also seek to serve multiple customer needs through relationship banking. Combining products such as accounts, savings, cards, mortgages and insurance can create a more integrated customer experience and deepen loyalty. But the relationship only creates value when products genuinely suit the customer; poorly targeted cross-selling can instead damage trust.

Subscribe to watch

Access this and all of the content on our platform by signing up for a 7-day free trial.

Simon Thompson

Simon Thompson

Simon Thompson is an accomplished executive with over 17 years of leadership in banking and finance, specialising in ethical and sustainable finance. As Managing Director of the Global Capacity Building Coalition (GCBC), he drives global efforts to enhance financial systems through capacity building and education. Previously, as Chief Executive of the Chartered Banker Institute, Simon transformed it into a global leader in socially responsible banking, advocating for ethics, culture, and sustainable finance. He is the author of "Green and Sustainable Finance: Principles and Practice".

There are no available Videos from "Simon Thompson"