Featured Pathways

More pathways

Banking Essentials - Part I

This pathway will walk us through the basics of banks, starting with some of the different types and their main functions, then starting to look at the regulation faced by the banks, both before and after the Global Financial Crisis.

Greenwashing

Greenwashing is the act of distributing false information about something being more environmentally friendly than it actually is.

More pathways

Book a demo

Ready to get started?

Plans & Membership

Our Platform

Expert led content

+1,000 expert presented, on-demand video modules

Learning analytics

Keep track of learning progress with our comprehensive data

Interactive learning

Engage with our video hotspots and knowledge check-ins

Testing & certification

Gain CPD / CPE credits and professional certification

Managed learning

Build, scale and manage your organisation’s learning

Integrations

Connect Finance Unlocked to your current platform

Featured Content

More featured content

Tackling the Cost of Living Crisis

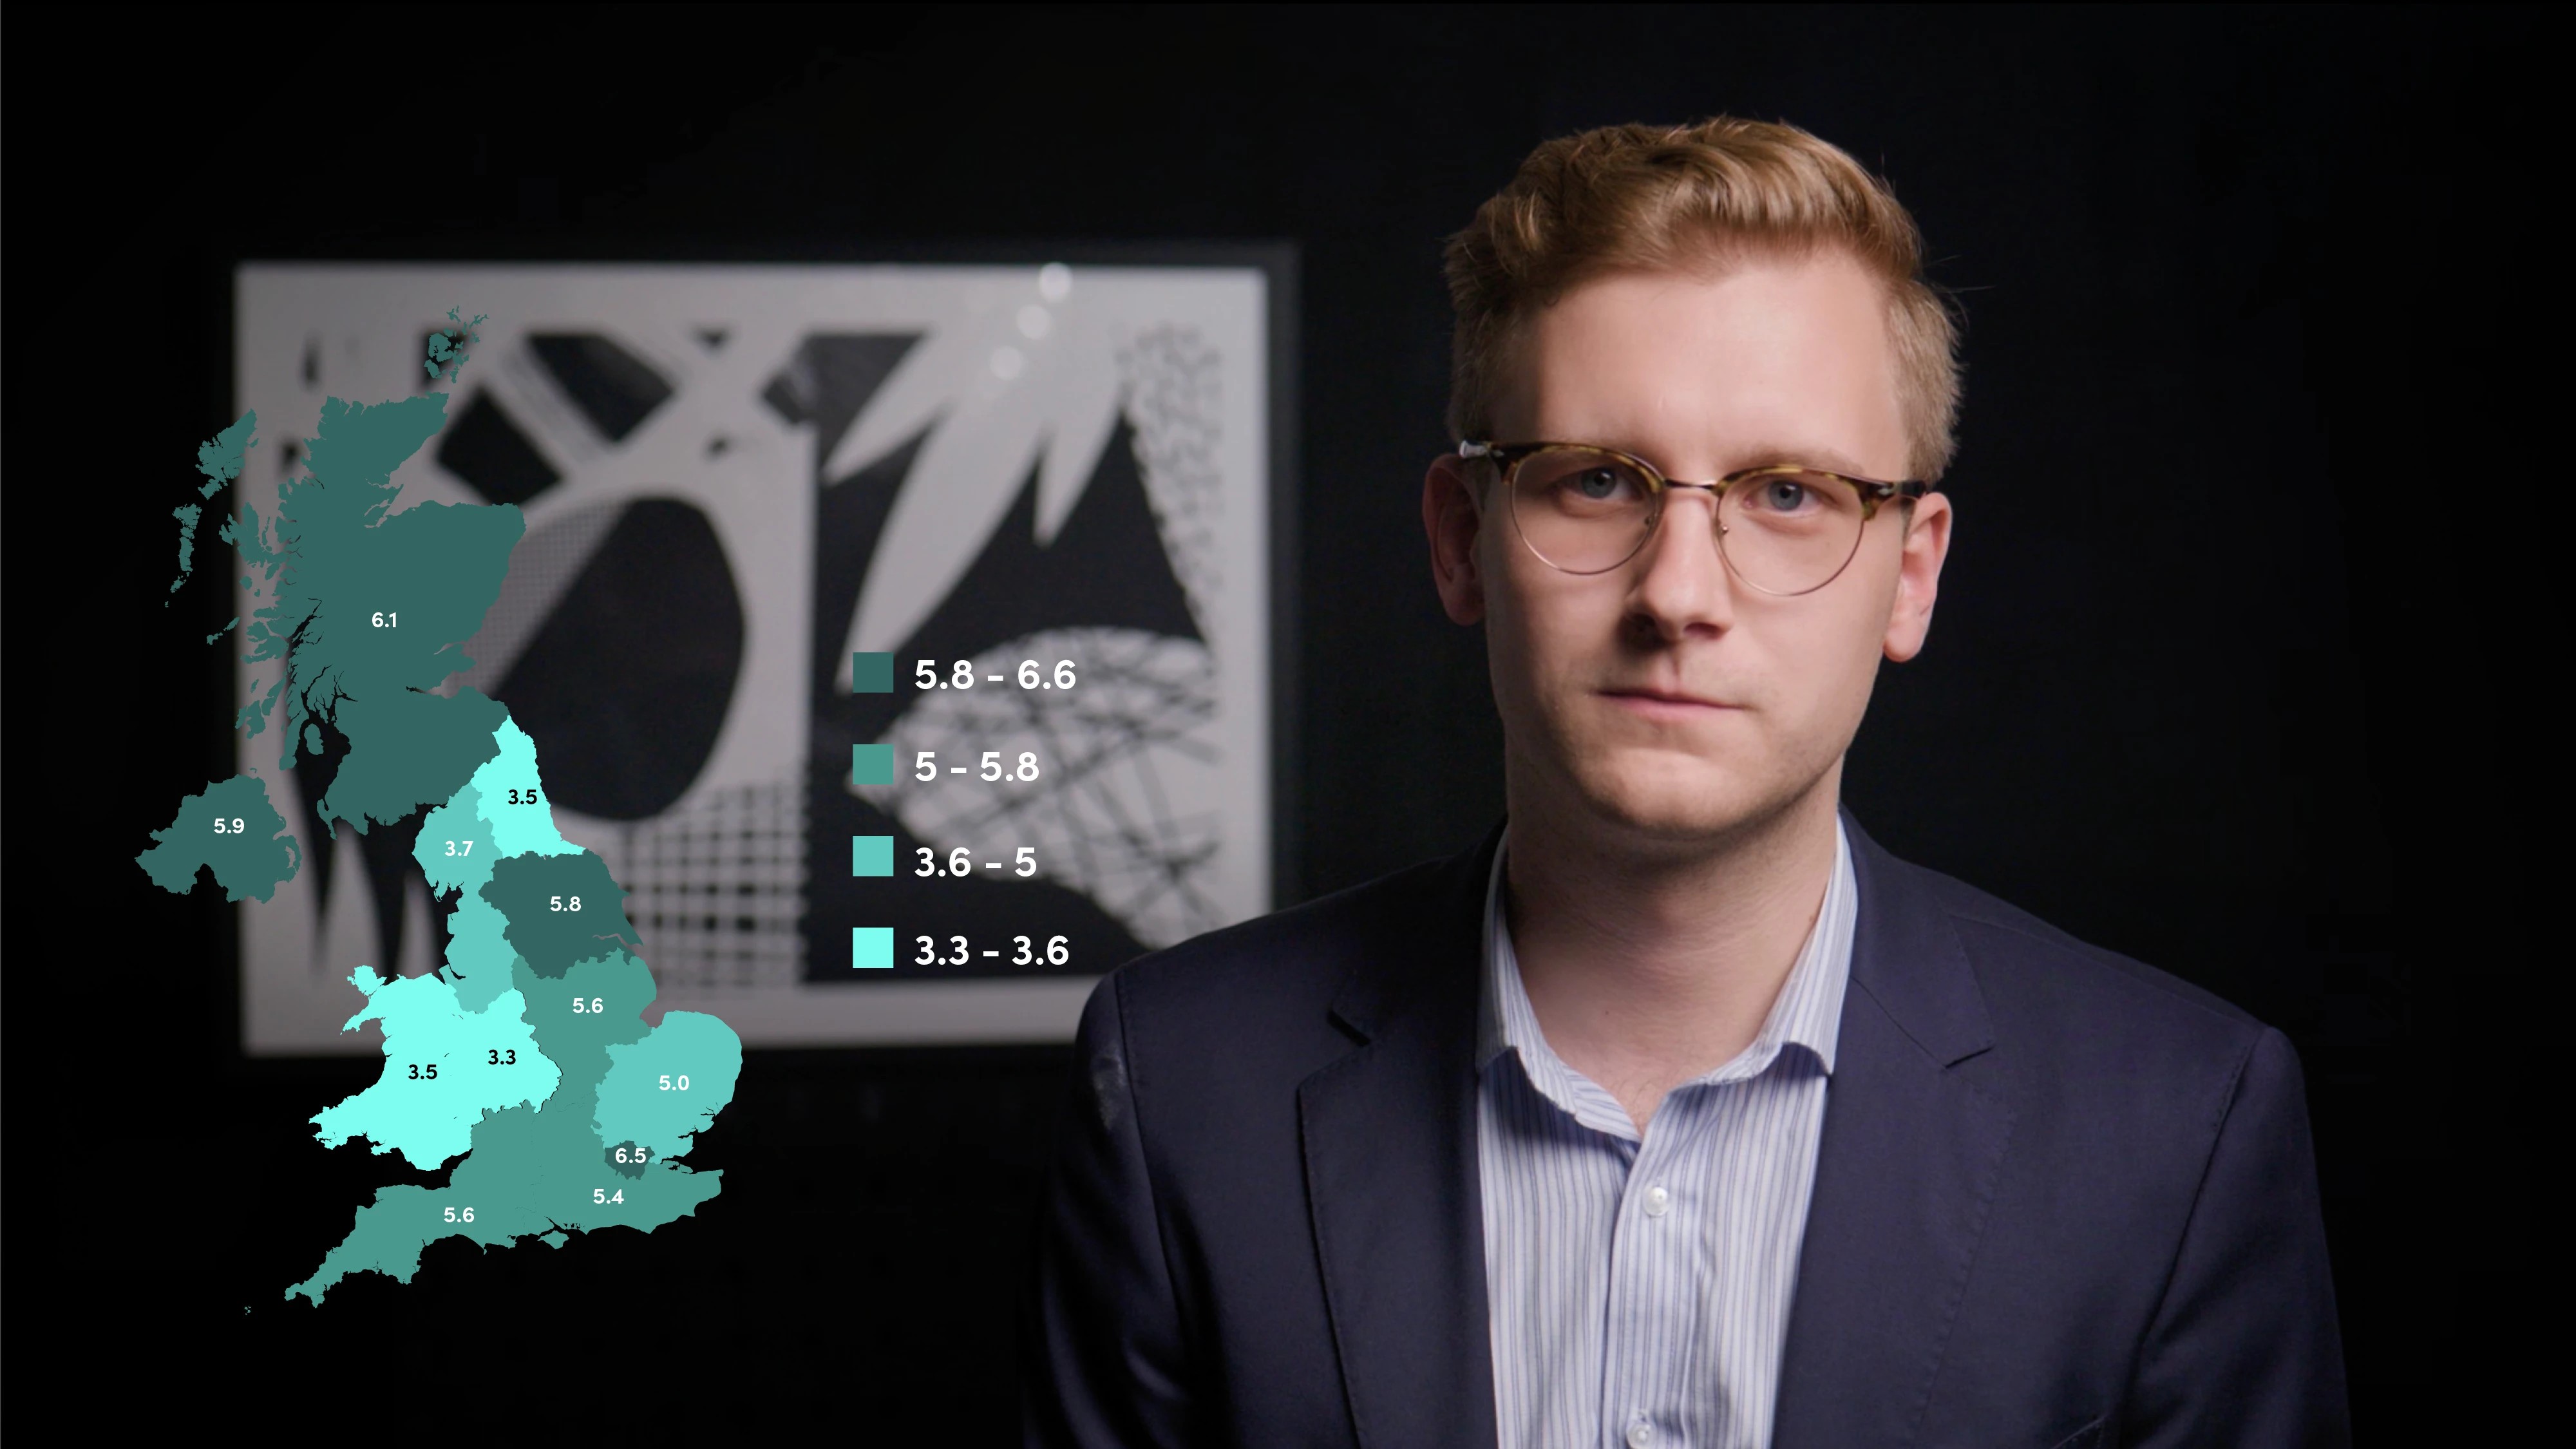
In this video, Max discusses the cost-of-living crisis currently enveloping the UK. He examines its impact on households as well as the overall economy.

Introduction to Corporate Valuation

In this video on Corporate Valuation, Sarah Martin covers the basic background to corporate valuations, who uses them, why they are needed and also outlines the factors that impact valuation.

More featured content

Book a demo

Ready to get started?

Featured Pathways

More pathways

Banking Essentials - Part I

This pathway will walk us through the basics of banks, starting with some of the different types and their main functions, then starting to look at the regulation faced by the banks, both before and after the Global Financial Crisis.

Greenwashing

Greenwashing is the act of distributing false information about something being more environmentally friendly than it actually is.

More pathways

Book a demo

Ready to get started?

Plans & Membership

Our Platform

Expert led content

+1,000 expert presented, on-demand video modules

Learning analytics

Keep track of learning progress with our comprehensive data

Interactive learning

Engage with our video hotspots and knowledge check-ins

Testing & certification

Gain CPD / CPE credits and professional certification

Managed learning

Build, scale and manage your organisation’s learning

Integrations

Connect Finance Unlocked to your current platform

Featured Content

More featured content

Tackling the Cost of Living Crisis

In this video, Max discusses the cost-of-living crisis currently enveloping the UK. He examines its impact on households as well as the overall economy.

Introduction to Corporate Valuation

In this video on Corporate Valuation, Sarah Martin covers the basic background to corporate valuations, who uses them, why they are needed and also outlines the factors that impact valuation.

More featured content

Book a demo

Ready to get started?

Book a demo

Ready to get started?

How Responsible Lending Decisions Are Made
How Responsible Lending Decisions Are Made

Simon Thompson

Sustainable Finance Expert

Understand how lenders assess affordability and creditworthiness, use credit scoring and human judgement, and support customers responsibly throughout the life of a loan.

Understand how lenders assess affordability and creditworthiness, use credit scoring and human judgement, and support customers responsibly throughout the life of a loan.

Subscribe to watch

Access this and all of the content on our platform by signing up for a 7-day free trial.
How Responsible Lending Decisions Are Made

5 mins

Key learning objectives:

  • Explain how lenders assess affordability and creditworthiness

  • Describe the roles of credit history, scoring models and human judgement

  • Recognise warning signs of poor lending standards

  • Explain how responsible lending continues throughout the life of a loan

Overview:

Responsible lending requires more than deciding whether a customer qualifies for credit. Lenders must assess whether borrowing is affordable, whether previous behaviour suggests the customer is likely to repay, and whether the credit is appropriate for their circumstances. Credit history, scoring models and collateral can support these decisions, but none provides a complete answer on its own. Where affordability is uncertain, further review may be needed, while unaffordable borrowing should be declined. Responsibility also continues after lending, particularly when customers experience financial difficulty and may require fair treatment, early engagement or forbearance.

Subscribe to watch

Access this and all of the content on our platform by signing up for a 7-day free trial.

Summary
How do lenders decide whether borrowing is responsible?

A responsible lending decision considers three related questions: can the customer repay, are they likely to repay, and is the borrowing appropriate for their circumstances?

Affordability is based on more than headline income. Lenders need to consider existing debt repayments, household expenditure, essential living costs and the customer’s capacity to absorb unexpected expenses. A customer may technically be able to make a repayment while still being left in a financially vulnerable position, so sustainable repayment capacity is more important than income alone.

What can credit history and collateral tell a lender?

Credit history can provide useful evidence about previous repayment behaviour, existing borrowing, missed payments and recent applications for credit. However, it may not reflect recent changes in circumstances or explain why previous difficulties occurred. It can also provide limited information for younger customers or people with little borrowing history.

Collateral is similarly useful but limited. Security such as a home or vehicle can reduce the lender’s potential loss if a borrower defaults, but it does not make the repayments affordable. Repossession should remain a last resort rather than substitute for proper affordability assessment.

How do models and human judgement work together?

Credit-scoring models allow lenders to process large volumes of applications consistently and efficiently by converting customer and financial information into an assessment of creditworthiness.

Models are particularly useful for applying consistent rules and identifying patterns, but they do not remove the need for governance or judgement. Additional review may be appropriate where information is incomplete, circumstances are unusual or the customer has limited credit history. Responsible lending combines scalable decision tools with fair, explainable outcomes.

What happens when lending becomes higher risk or circumstances change?

If borrowing is affordable, lenders can consider suitable terms and pricing. If affordability is uncertain, further information or review may be required. If repayments are not sustainable, increasing the interest rate does not solve the underlying problem; the responsible outcome may be to decline the application.

Responsibility also continues after credit has been granted. Job loss, illness, bereavement or higher household costs can make an initially affordable loan difficult to manage. Early engagement, clear communication, fair collections and appropriate forbearance can help customers through financial difficulty while reducing longer-term harm.

Subscribe to watch

Access this and all of the content on our platform by signing up for a 7-day free trial.

Simon Thompson

Simon Thompson

Simon Thompson is an accomplished executive with over 17 years of leadership in banking and finance, specialising in ethical and sustainable finance. As Managing Director of the Global Capacity Building Coalition (GCBC), he drives global efforts to enhance financial systems through capacity building and education. Previously, as Chief Executive of the Chartered Banker Institute, Simon transformed it into a global leader in socially responsible banking, advocating for ethics, culture, and sustainable finance. He is the author of "Green and Sustainable Finance: Principles and Practice".

There are no available Videos from "Simon Thompson"